 Staff Report
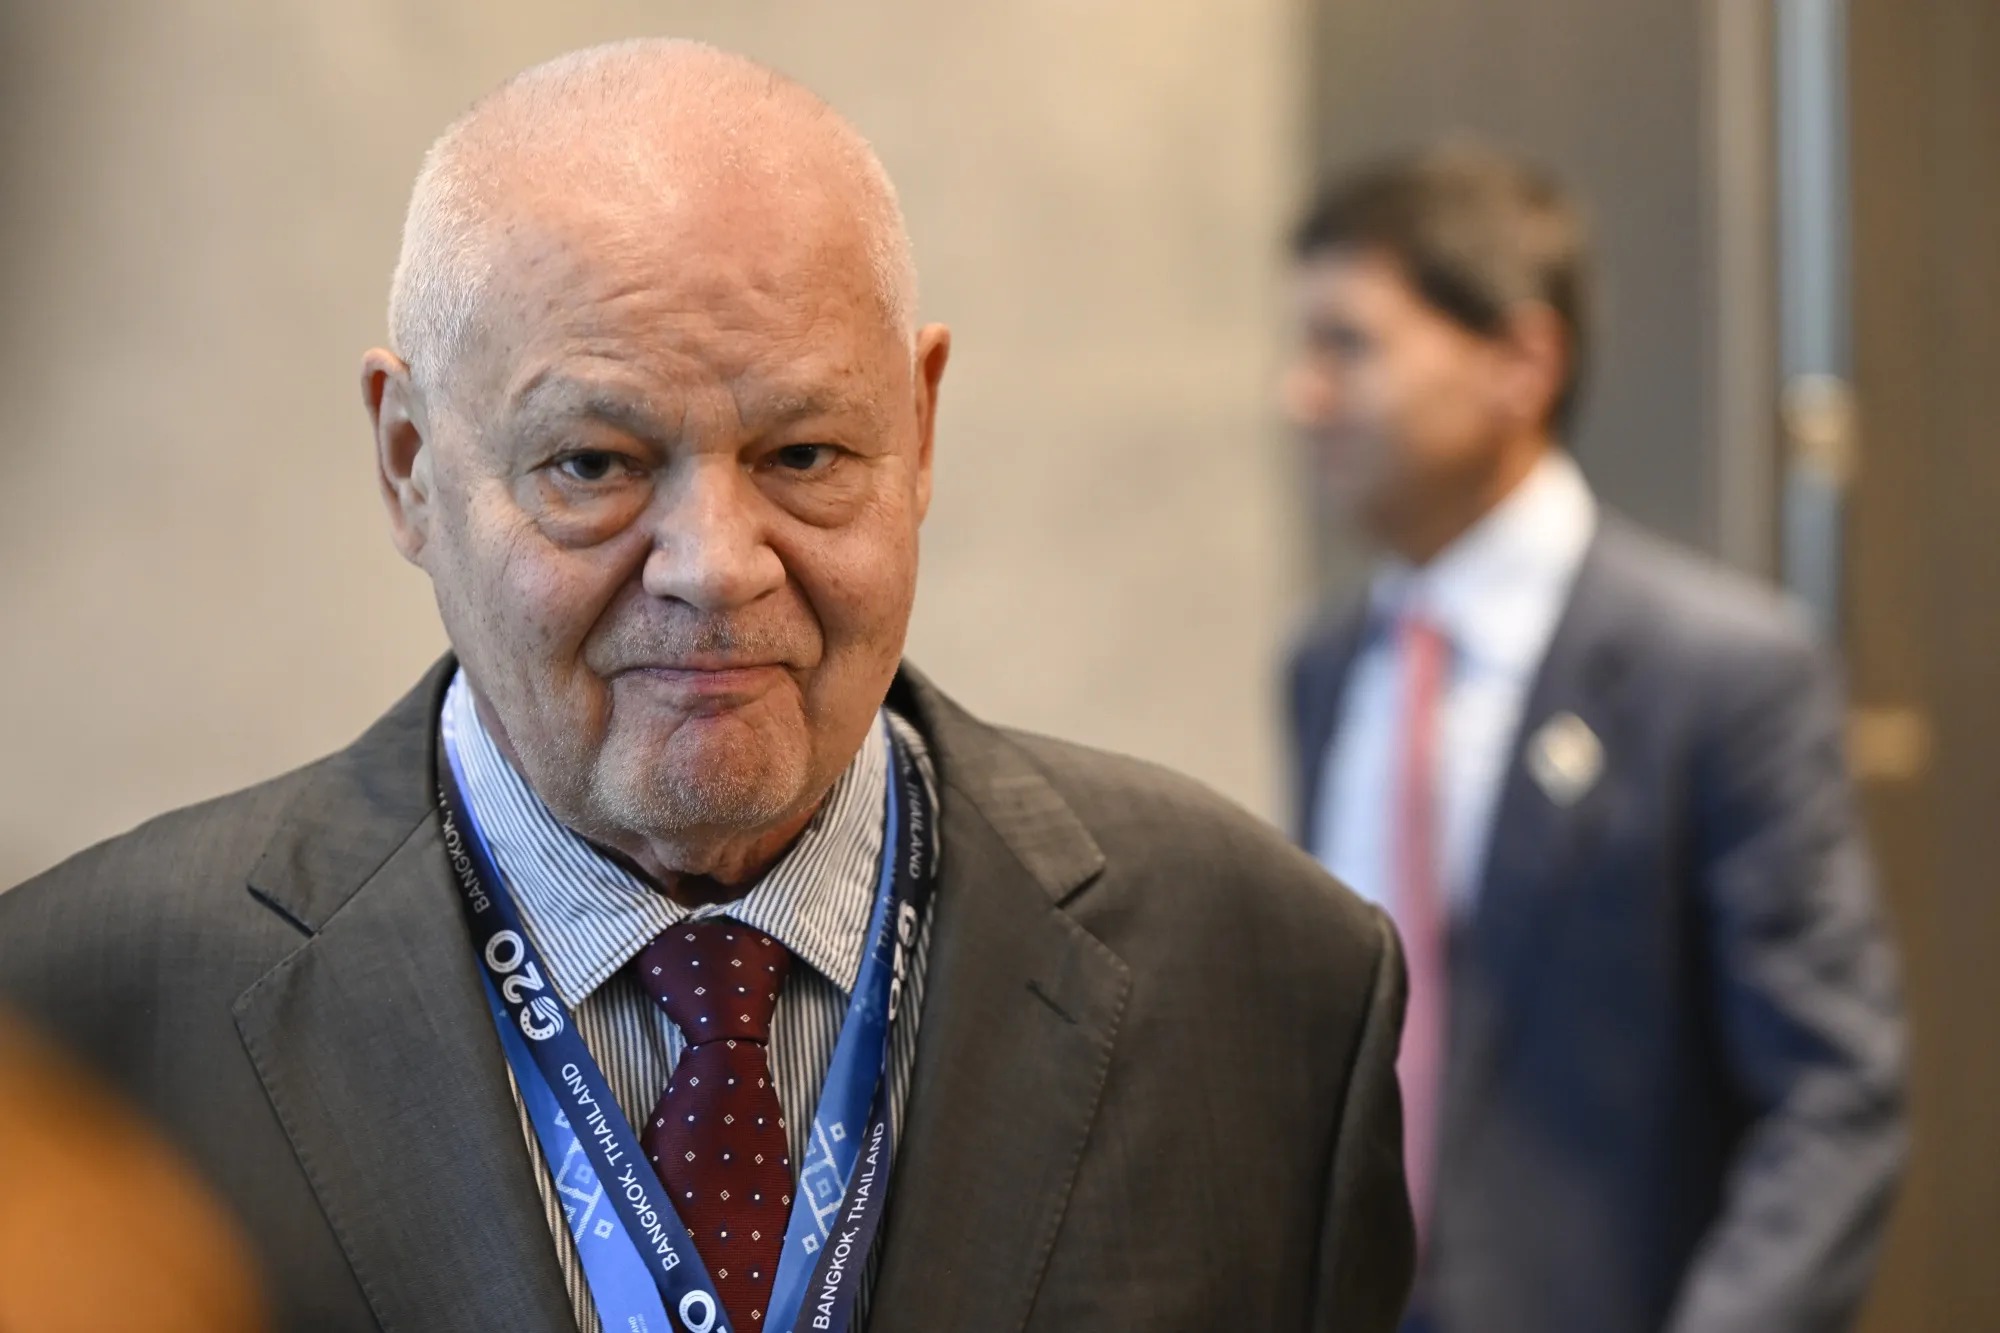
Poland’s central bank has become the stage for an escalating political standoff between its governor, Adam Glapinski, and Prime Minister Donald Tusk’s government, with lawmakers weighing a State Tribunal case against him just as his leadership term approaches a contested expiration date of 4 November.
The timing compounds the uncertainty. With Glapinski’s term set to lapse right as the tribunal question hangs over him, it remains unclear whether Poland’s Monetary Policy Committee, the body responsible for setting interest rates, can even convene its scheduled meetings without a confirmed central bank chief in place, a logistical problem layered on top of the underlying political dispute.
That ambiguity has started showing up directly in currency markets. The Polish zloty has come under pressure against the euro as the institutional tension at the National Bank of Poland deepens, with traders treating the standoff as a genuine source of policy uncertainty rather than background political noise, given how directly it touches the body that actually sets the country’s monetary policy.
The confrontation fits into a broader pattern that has defined Glapinski's tenure under Tusk's government: a central bank leadership widely seen as aligned with the previous Law and Justice administration, now facing sustained pressure from a governing coalition eager to assert more direct influence over an institution it views as a holdover from its political opponents. A tribunal case, Poland's mechanism for holding senior officials formally accountable, would mark a significant escalation beyond the political sniping that has characterized the relationship until now.
For a central bank, the stakes of this kind of standoff extend well beyond the personalities involved. Markets generally price central bank independence as a stabilizing factor, and a prolonged fight over who legitimately holds the top job, paired with real questions about whether the rate-setting committee can function normally, is precisely the kind of institutional uncertainty that tends to get reflected in a currency's value before the underlying political question is even resolved.
With the term expiration date now arrived and the tribunal question still unsettled, Poland is left with a central bank whose leadership legitimacy is actively disputed at the exact moment its rate-setting body needs to keep functioning, a combination that leaves both domestic markets and anyone watching Polish monetary policy from abroad waiting to see how, and whether, the standoff gets resolved without further damage to the institution's credibility.