 Staff Report
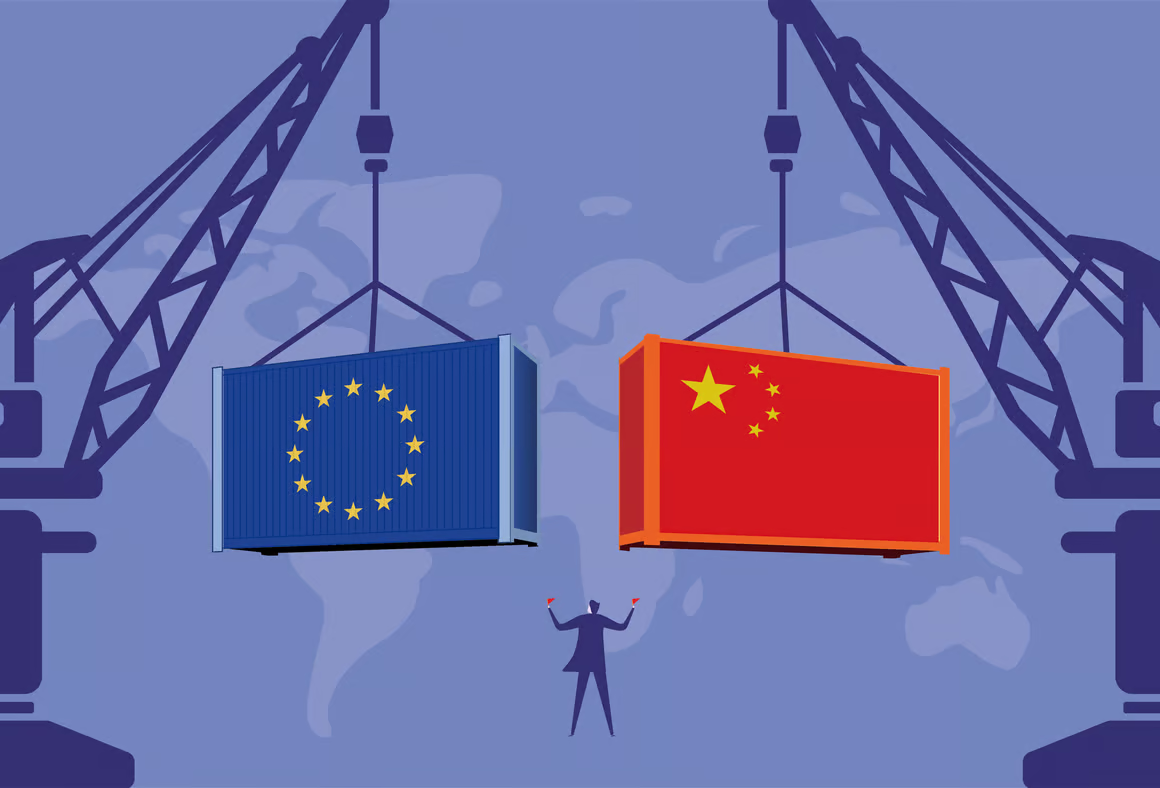
The cost of insuring French government debt against default has climbed to its highest point since the European sovereign debt crisis over a decade ago, a stark indicator of growing investor unease. This surge in the credit default swap (CDS) market reflects mounting concerns about the nation’s fiscal health, particularly after the recent snap election announcement by President Emmanuel Macron amplified political uncertainty and cast a shadow over the government’s ability to manage its budget deficit. The spread on five-year French CDS, a key measure of perceived risk, has widened significantly, signaling a tangible shift in how markets view the eurozone’s second-largest economy.
For weeks, anxiety has been building around France’s public finances. Rating agencies like S&P Global Ratings have already downgraded the country’s sovereign debt outlook, citing a larger-than-expected budget deficit and a challenging path to fiscal consolidation. The government’s projection for its deficit to fall to 5.1% of GDP this year, down from 5.5% in 2023, is now viewed with skepticism by some analysts and investors. The political landscape, fractured and unpredictable following Macron’s decision to dissolve parliament, only complicates these economic forecasts, making it harder to envision a clear strategy for debt reduction.
The ripple effects of this growing apprehension are not confined to the CDS market. The yield on France’s benchmark 10-year government bonds has also seen a sharp increase, pushing the spread over the safer German equivalent to levels not witnessed in years. This widening spread, often seen as a barometer of perceived risk within the eurozone, indicates that investors are demanding a higher premium to hold French debt. Such movements can translate into higher borrowing costs for the French state, potentially exacerbating the very budget challenges that are driving the current market jitters.
Political uncertainty invariably translates into economic volatility, and France is currently a prime example. The upcoming legislative elections, scheduled for late June and early July, introduce a period of intense speculation regarding the composition of the next government and its economic policy direction. Different political factions have put forward varying fiscal proposals, some of which could lead to increased public spending or tax cuts without clear funding mechanisms, further straining the national budget. This lack of a predictable fiscal path makes it difficult for investors to assess future economic stability.
While the current situation is serious, it is important to contextualize these developments. France remains a core member of the eurozone and benefits from the institutional stability provided by the European Union. The European Central Bank also possesses tools to intervene in times of severe market stress, though such interventions are typically reserved for extreme circumstances. However, the current trajectory serves as a potent reminder that even large, developed economies are not immune to market scrutiny, especially when fiscal discipline and political predictability waver. The coming weeks will be crucial in determining whether France can reassure markets and steer its public finances back onto a more sustainable course.