 Staff Report
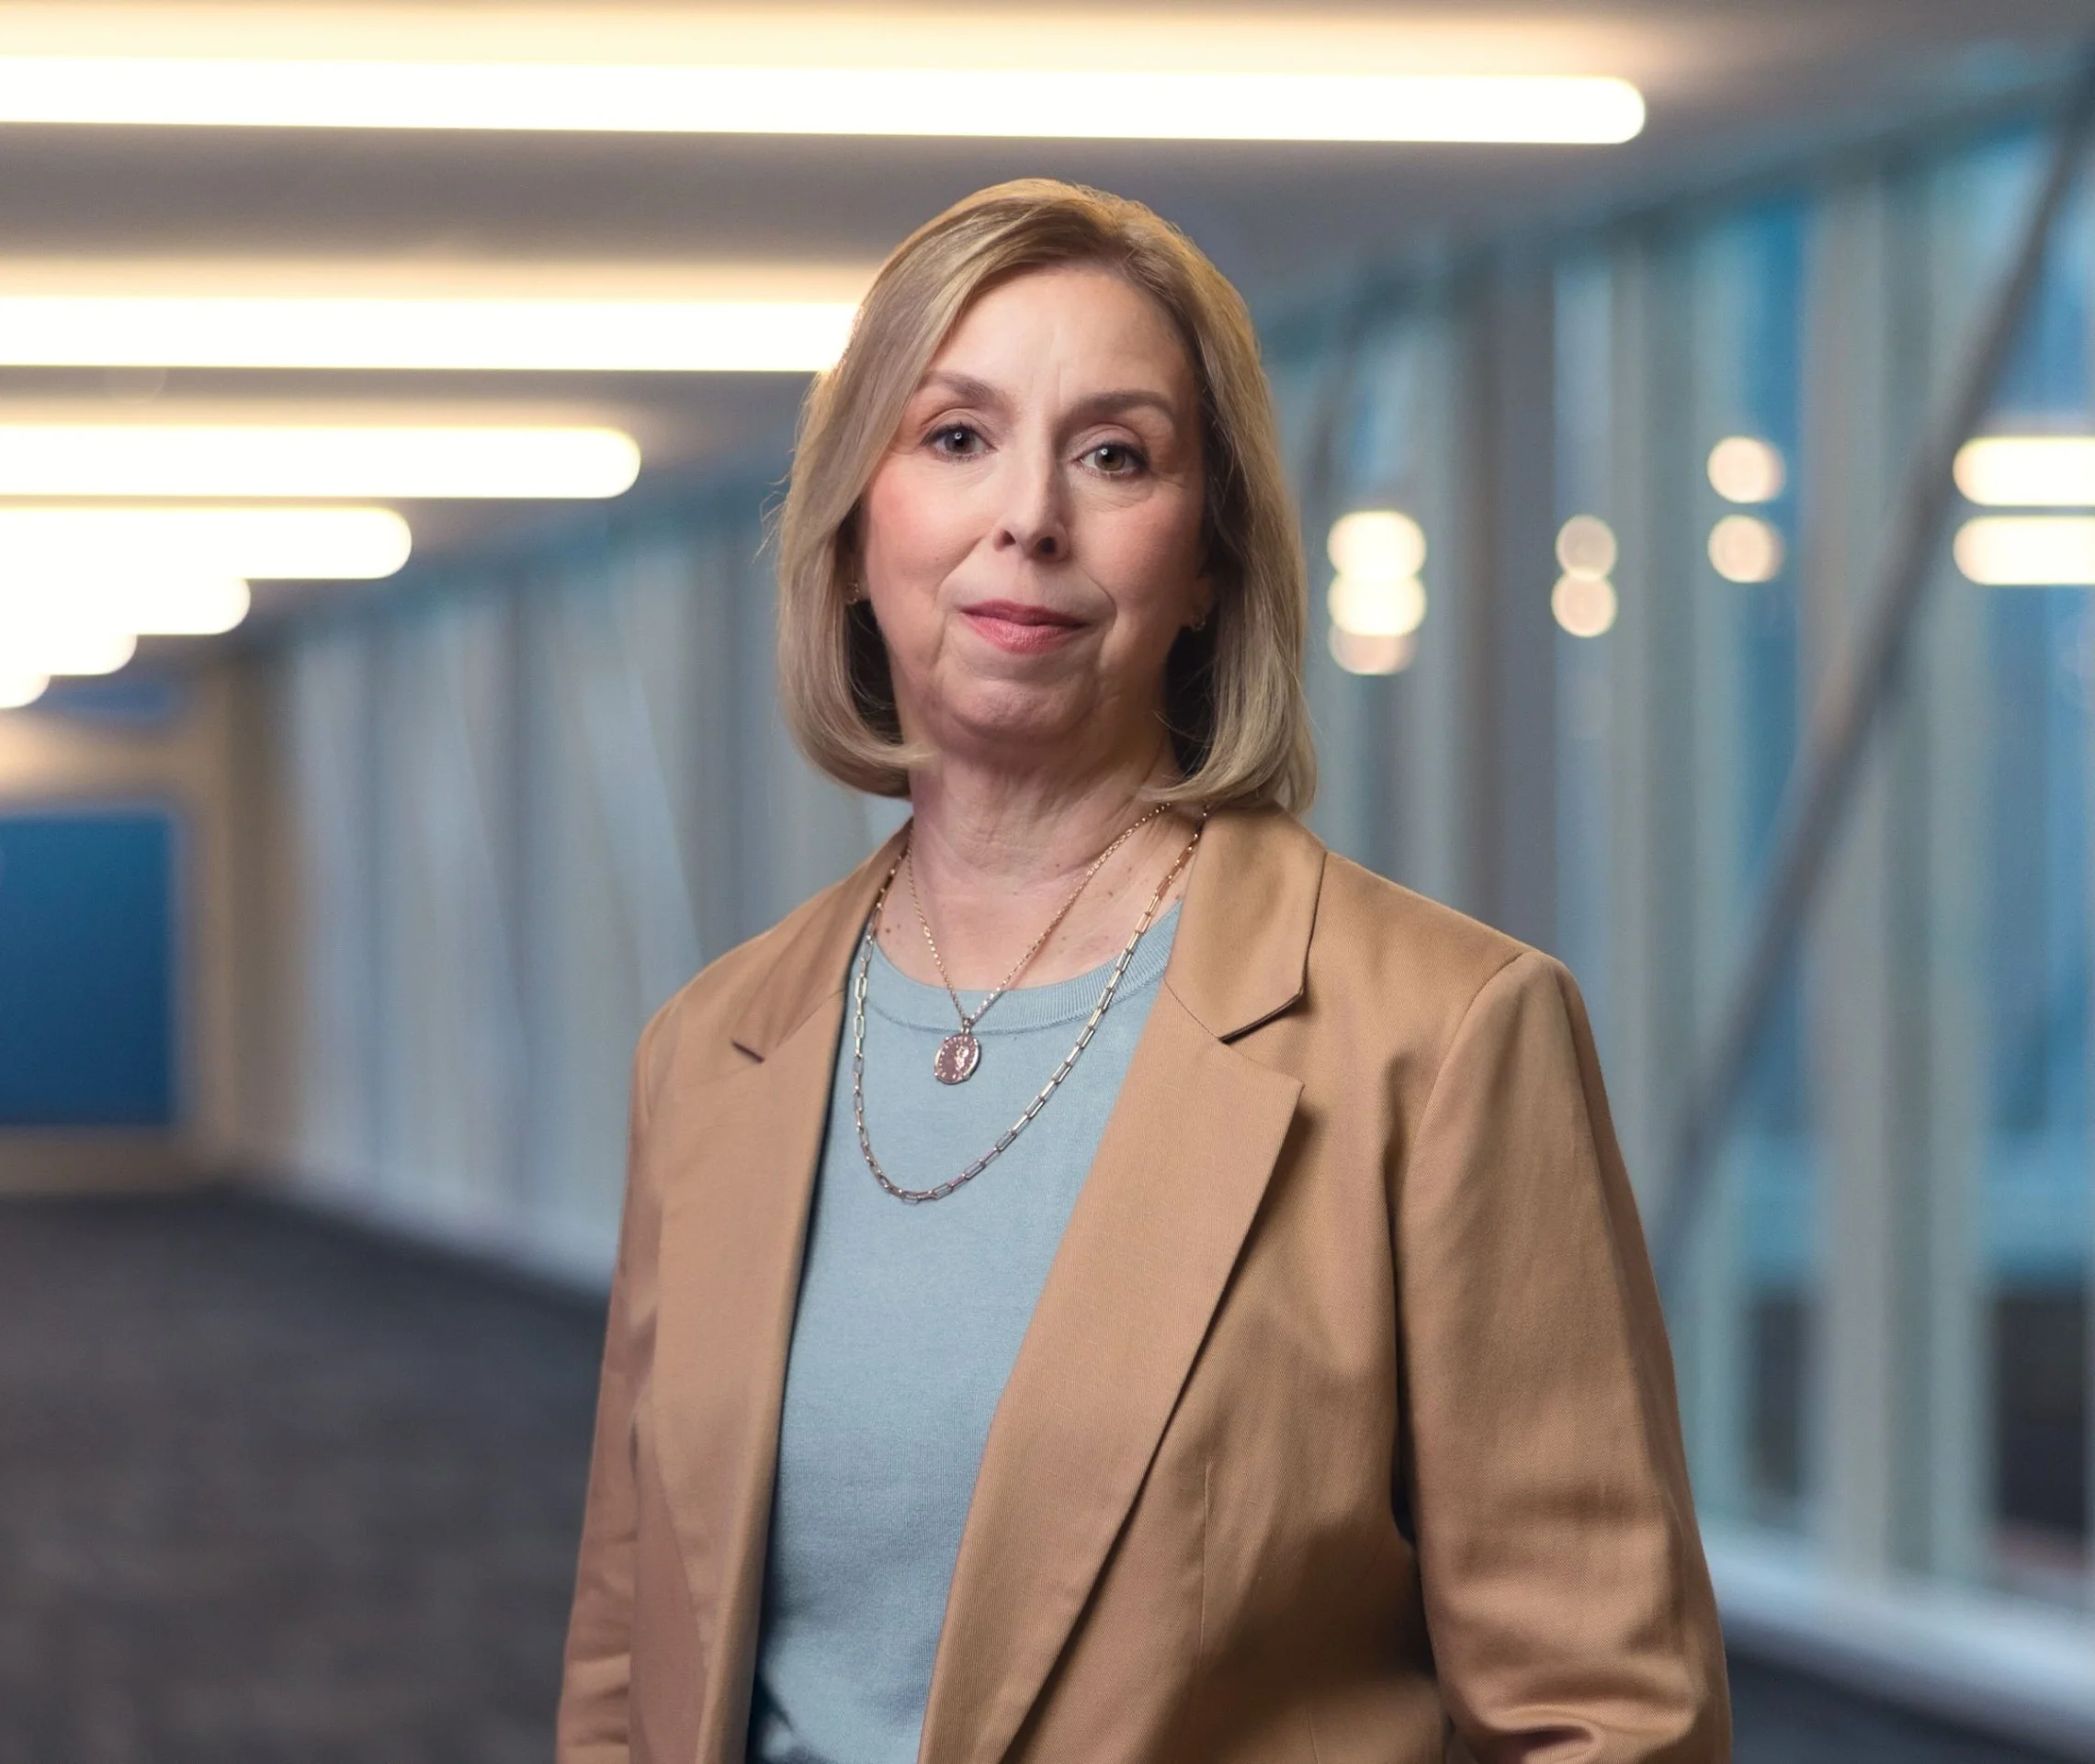
Europeans are living longer than ever, and the region’s employers are not ready for what that means for the workforce. More than one fifth of the European Union’s population is already 65 or older, and the share aged 80 and above is projected to more than double by the end of the century. Deanna Strable, chief executive of Principal Financial Group, believes neither companies nor their employees are prepared for the consequences.
The workforce is aging fast
Falling birth rates mean fewer young people are entering the labor market, while millions of baby boomers are reaching retirement age. The result is that older workers make up a growing share of those in employment. In 2025, a record two thirds of 55 to 64 year olds in the EU were in work, according to Eurostat. As careers stretch out, Strable says, employers will have to adjust hiring practices, job design, and training so they work for people later in their careers.
“Employers and leaders are going to have to get used to people being in the workforce for a longer amount of time,” Strable says. “I don’t think we’re all prepared for that.”
What one employer is trying
Strable has led Principal since January 2025. The U.S. based retirement and asset management company advises more than 200,000 American employers and manages money for European pension providers. Its own payroll now spans five generations, so the firm has had to think practically about how to keep a multigenerational workforce productive.
Over the past 18 months, Principal has trained all 19,000 of its employees in artificial intelligence, offering the courses in different formats because some people prefer self paced learning while others want to sit around a table with colleagues. It has also expanded its rotation programs, which once were limited to actuaries, into IT, accounting, and finance. The idea is to let staff move into new roles as their careers lengthen, rather than push them to change employers to advance.
Strable, who has spent her whole career at Principal across 15 different roles, thinks the company lifer could make a comeback. Workers may increasingly look for employers that will help them adapt, she argues, rather than gamble on starting over somewhere else. “You can have the equivalent of 10 different jobs with one company,” she says, “or you can start over at 10 different companies.”
Longevity has a gender problem
Longer life expectancy also means people will need to save more for retirement, unless they stay economically active for longer. That pressure risks making the pension gender gap worse. A woman in the EU will spend about four fewer years in paid work than a man, yet she can expect to live five years longer. By retirement, her pension is typically 24.5 percent smaller than a man’s, more than twice the size of the gender pay gap.
Women tend to earn less, work part time more often, and take career breaks to care for others, all of which leave them with smaller retirement savings. A woman born in the EU today can expect to live to 84, and the European Commission projects that will pass 90 by the end of the century. That smaller pot will have to cover more years of retirement. “That is something we all should be paying attention to because it could actually make things much worse,” Strable says.
Confidence in state pensions is low
Across Europe, responsibility for retirement is shifting from governments and employers to individuals. The United Kingdom has automatically enrolled workers into workplace pensions since 2012, Ireland followed in January 2026, and the Netherlands is replacing guaranteed pensions with personal savings pots. These measures get more people saving, but they also place more of the burden on savers themselves.
Women are less confident than men that the state will be enough. Only 29 percent of European women believe their government's pension system will fund their retirement, compared with 39 percent of men, according to Principal's latest Global Financial Inclusion Index. In Germany, the figure for women falls to 17 percent.
Auto-escalation and timely advice
Strable argues the workplace remains the most important place for retirement saving, which gives employers real influence over how much people put aside. She recommends combining auto-enrollment with auto-escalation, a feature common in U.S. plans but rare in Europe, so contributions rise gradually rather than staying at the minimum. Someone who starts saving 5 percent might want to reach 12 percent, but that jump feels daunting. Tying each increase to an annual pay rise makes it manageable.
Women's savings often slip at predictable moments, such as starting a family, caring for a relative, or losing income. Employers are often the first to know about those moments through parental leave, carer's leave, or sick pay, Strable says, putting them in a strong position to help staff review their savings.
Yet employer provided financial guidance has fallen across advanced economies for two years in a row, according to Principal's index. That is happening when women already feel less equipped to plan ahead: only 54 percent of European women say they can easily access the tools they need to plan a secure retirement, compared with 64 percent of men.
"Many women are left without professional financial advice, often at the moment they need it most," Strable says. In many households, the husband dealt with the advisor, so a widow may have no link to the person who knows the family's finances. Insurer Liverpool Victoria has found that 41 percent of UK women would not feel confident managing household finances if their partner died.
The bigger picture for employers
For Strable, financial security is part of a broader goal: helping people live longer, healthier, and happier lives, with the resources to enjoy those extra years. As careers lengthen, the workplace itself becomes more important. "A CEO's number one job is to create a culture where people want to stay and work," she says. Building that kind of workplace could become a genuine competitive advantage as Europe's population ages.